From venture capital
Venture conviction
- We take
- Early, thesis-driven conviction on structural change, and the patience to let it compound.
- We leave
- Ten-year lock-ups, blind pools and a price set once a funding round.
Beyond Human Patterns · Singapore
SUPERREALIS is a Singapore principal investment firm. We invest our own capital where intelligence meets the physical world: the compute, power, materials and machines that artificial intelligence now depends on, much of it built across Asia.
The firm
We invest solely our own capital. We do not manage money for others, accept outside investment or provide advice. That choice is the foundation of everything else we do.
We are built as an AI-native investment organisation. Without clients to answer to, we can hold a view for as long as the evidence supports it, and step aside the moment it does not.
Our core discipline is long/short equity, informed by macro regime analysis and concentrated on one structural shift: intelligence is becoming physical. Models need chips, chips need power, power needs grids and materials, and machines are beginning to act in the world. Each link in that chain is repriced as the shift accelerates, and rarely in the order consensus expects.
We are deliberately lean and deliberately rigorous. Fundamentals come first, then timing, then trade structure, then risk. Every trade carries a pre-trade record and a post-trade review, and alpha is measured against a beta-adjusted benchmark, so the return earned by skill is never confused with the return earned by market exposure.
Our blue ocean
Venture capital sees structural change early, then waits years, locked up, for a price. Public markets offer liquidity and price discovery, yet rarely look beyond the next quarter. Institutional allocators govern risk superbly, but stand far from the thesis.
The space none of them occupies is ours: venture-grade theses on intelligence becoming physical, held long and short in liquid listed markets over horizons from 20 days to full cycles of 4 to 12 years, priced against the regime, sized in units of volatility and governed like an institution, with permanent capital of our own.
From venture capital
From public markets
From institutional allocation
We take the risks that matter in the age of singularity, as intelligence and humanity evolve together.
Firm console
What we believe, where we choose to compete and how risk is bounded. The console is illustrative throughout: it describes how we work, never what we hold.
Vision
To be the independent investment firm that best understands where intelligence meets the physical world: seeing the real economy beneath the narrative, and investing in what intelligence needs in order to exist rather than in what it promises to become.
Mission
To compound our own capital across market regimes by investing in structural change, with every trade recorded before and reviewed after, every mandate countersigned independently, and risk bounded by an envelope that only tightens.
Mandate
Proprietary capital only. No third-party funds, no advisory services, no solicitation.
01
Why it is hard to copy
Each established model is strong where the others are weak. Our value curve takes the peaks of all three and drops what none of them can shed: lock-ups, outside-investor pressure and layers of cost.
Select a factor to read how we position on it.
Eliminate
Reduce
Raise
Create
Qualitative positioning against industry models. Not a measurement of any firm.
We hold positions on two horizons and let permanent capital carry the structural book across several cycles. The horizon is set by the thesis and the regime, never by a fund life or a redemption date.
Horizons describe how the firm invests, not current holdings.
Approach
Investing in structural change starts with one observation: artificial intelligence is no longer only software. It runs on silicon, power, cooling, metals and machines. The largest mispricings form where that convergence moves faster than consensus can model it. We follow it link by link, long and short.
Models, software and the platforms that distribute them, where scale compounds and disruption is priced late.
Semiconductors, networking and the data centres that turn electricity into intelligence.
Generation, grids, storage and cooling: the binding physical constraint on every digital ambition.
The metals, components and manufacturing capacity that make the transition physical.
Robotics, automation and autonomous systems: intelligence beginning to act in the physical world.
Strategy profiles
Relative emphasis by profile. Not portfolio weights.
Process
Two engines run through every decision. The alpha engine decides where capital could earn its return. The risk engine decides how much it may, and when to step back.
Idea formation
Risk engine
Alpha engine
Volatility, liquidity, correlation and market regime are read as state variables before any view is taken.
Fundamentals come first: what a business is worth, and where the market has mispriced it.
Then timing: the catalyst, and the regime in which the view can be paid.
Then trade structure. Relative-value and hedged positions are modelled as spreads, not outright bets.
Statistical analysis and modelling come first; the position is then sized in units of volatility, inside the envelope.
Every trade carries a pre-trade record. Any limit reached is notified to every director within a business day.
Every trade carries a post-trade review, and alpha is measured against a beta-adjusted benchmark.
Risk architecture
We do not fear volatility. We measure it, price it and trade it. Every move is read in sigmas against its own regime, every position is sized in units of risk, and the drawdown freeze is the one line we never cross.
Keep the return we came for. Hedge the risk we are not paid for.
r = α + βmktfmkt + βstylefstyle + βthemeftheme + ε
Our interpretation: the structural theme is an exposure we choose deliberately. Most public funds hedge it away as noise; venture investors cannot hedge anything at all.
A move means nothing until it is measured against its regime and its horizon.
Real returns have fatter tails than the bell curve, so we size for them with tail measures such as conditional value at risk.
Independent bets add like the sides of a right triangle, not in a straight line.
Correlation is hidden leverage: as it rises, two bets become one. We concentrate only where bets are truly independent.
From raw data to a position sized in units of volatility, and back to attribution.
Illustrative parameters throughout. The panels show the method, not the firm's positions, limits or results.
Machines find the patterns. People sign the decisions.
Governance
Governance at SUPERREALIS exists to make boldness safe. Limits are written, signed and reviewed on a fixed cycle; inside them, decisions are fast. Between reviews the envelope can tighten, never relax.
Approves the quarterly mandate and may direct a reduction of risk at any time.
Set jointly by the Chief Executive Officer and the Chief Investment Officer in the Market Overview.
The Portfolio Manager invests within the approved envelope and is bound by it.
Weekly risk reports and a Quarterly Report, each signed by both officers.
Quarter-end: the Board reviews the record and approves the next mandate.
Each mandate fixes the drawdown at which new risk is frozen, the gross and net exposure ranges, the largest single position, the permitted instruments and margin use, and the liquidity horizon.
Between Board reviews, the two officers may jointly stop trading or tighten the envelope at any time. Neither may relax it.
Every Market Overview, Quarterly Report and weekly risk report carries both officers' signatures. The Chief Executive Officer's countersignature is the independent check.
The Board may direct a reduction, hedge, freeze or closure of the portfolio at any time. Any drawdown above ten per cent is disclosed in the Quarterly Report.
Any limit that is reached or exceeded is notified to every director within one business day. The officers review risk weekly; the Board meets monthly.
Alpha is reported against the declared beta multiplied by the S&P 500 Total Return, plus cash for the remainder. Skill is separated from market exposure.
Leadership
Two founders from the two sides of our thesis: the physical economy of shipping, logistics and commodities, and the machine intelligence of quantitative research. Equal rank, distinct duties. One invests; the other holds the investment to account.
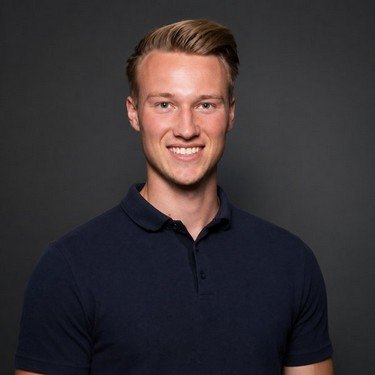
Co-Founder · Chief Executive Officer · Chairman of the Board
Koen chairs the Board and leads governance, risk oversight and capital administration, countersigning every mandate and risk report as the firm's independent control over the portfolio. An early-stage investor in a diversified portfolio spanning digital assets and blockchain infrastructure, shipping and logistics, and commodities and metals, Koen manages several private investment ventures alongside SUPERREALIS. Koen's career began in international logistics and maritime trade in Rotterdam.
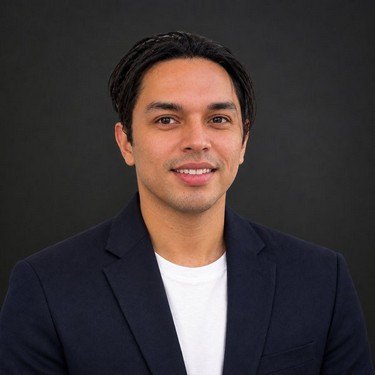
Co-Founder · Chief Investment Officer · Portfolio Manager
Fredy leads research, portfolio construction and trading within the mandate approved by the Board, with a focus on the physical build-out of artificial intelligence, from compute through power, grid, cooling and networking. Fredy also leads SINTESIS, an independent quantitative research firm in Berlin specialising in algorithmic trading; SINTESIS is a separate company and is not affiliated with SUPERREALIS. Previously, Fredy founded and directed a prize-winning public commission for the Cidade da Cultura de Galicia in Santiago de Compostela, leading architects, engineers and installers.
Singapore
The physical layer of intelligence is largely made in Asia: fabrication in Taiwan, memory in Korea, equipment and materials in Japan, assembly, packaging and data centres across Southeast Asia. Singapore keeps all of it in view, and keeps us between the world's capital markets.
A common-law jurisdiction with deep, well-regulated capital markets.
Between Asia's supply chains and the capital markets of Europe and the Americas.
A framework that distinguishes firms investing their own capital from those managing other people's.
Close to the companies, supply chains and policy shifts that decide how fast intelligence becomes physical.
Contact
SUPERREALIS does not accept outside capital or offer investment services. For corporate, counterparty and media enquiries, please write to us.
office@superrealis.com